
Which health insurance do you need as an expat on the Costa Blanca?
By our editorial team, with Raquel Domínguez, insurance mediator in Palma de Mallorca
In short: according to Raquel Domínguez, an insurance mediator, the monthly price is the least telling figure in a health insurance policy. Before choosing, you need to know whether you are entitled to the public system or to the convenio especial (€60 a month under 65), then read the architecture of the policy: network or reimbursement, real limits, exclusions, waiting periods, pre-existing conditions, maximum joining age and renewal clause.
Most newcomers pick their first health insurance by comparing monthly premiums. Yet, according to Raquel Domínguez, that is often the figure that tells you least about the contract. "What determines whether a policy protects you is its architecture," she explains: the benefits, the exclusions, the limits and sub-limits, the authorisations, the waiting periods and the medical underwriting.
Who needs private health insurance on the Costa Blanca?
For a new resident, a private policy may be a legal condition of the residence permit and, for many, the main route to healthcare until they qualify for the public system. Three situations are concerned:
- non-EU nationals applying for a non-lucrative residence visa;
- applicants for the digital nomad visa;
- residents with no access to public healthcare: they do not pay into Spanish Social Security through work, have no entitlement through their home country (the S1 form held by European pensioners, for example) and do not yet meet the conditions for the convenio especial.
The SIP health card confirms an entitlement to public healthcare; it does not create one.
What must the insurance cover for a residence visa?
For the non-lucrative residence visa, the consulate asks for a policy taken out with an insurer authorised in Spain, covering the same risks as the public system. The consulate's own text does not mention copayments or waiting periods, but in practice, according to Raquel Domínguez, consulates generally ask for a policy with neither. Other permits, such as the digital nomad visa, have their own requirements. For the mediator, meeting them is an administrative minimum, not a genuine assessment of your protection.
The checklist before you sign:
- an insurer authorised to operate in Spain;
- cover equivalent to the public system;
- no copayments and no waiting periods;
- cover valid throughout Spain;
- a certificate from the insurer stating these points, to attach to your application.
The convenio especial: a public alternative, for whom and at what price?
The convenio especial (Real Decreto 576/2013) is a paid membership of the public health system, for residents who are not otherwise entitled to it.
What are the conditions?
- being registered on the municipal register (empadronamiento);
- having no access to public healthcare on any other basis;
- proving at least one year of continuous, effective residence in Spain immediately before applying. Periods of residence in another European Union country, the European Economic Area (EEA), Switzerland or the United Kingdom can be taken into account.
You apply to the health service of your autonomous community: the Generalitat Valenciana in Valencia and on the Costa Blanca (procedure no. 17044), IB-Salut in the Balearic Islands.
How much does the convenio especial cost? €60 a month under 65, €157 a month from the age of 65.
What does it not cover? Medication bought at the pharmacy, orthotics and prostheses, dietary products and non-urgent medical transport.
Because it requires you to be already registered in a Spanish municipality, it cannot be used for a visa applied for from abroad.
Convenio especial or private insurance: which should you choose?
| Convenio especial | Private health insurance | |
|---|---|---|
| Access | after one year of residence | from arrival |
| Visa applied for from abroad | no | yes, with no copayments or waiting periods |
| Pharmacy medication | not covered | depends on the policy |
| Doctors | public network | insurer's network, or free choice with reimbursement |
| Monthly cost | €60 (€157 from 65) | varies with age and benefits |
Should you choose a network policy or a reimbursement policy?
A network policy (cuadro médico) gives access to a defined list of doctors and hospitals, sometimes with copayments (copagos). These are usually capped per person per year, and unpaid copayments can suspend your cover. A reimbursement policy (reembolso) leaves you free to choose your doctor: you pay the invoice, then the insurer refunds a percentage, typically 80% or 90%. Many products combine the two.
"The most common technical error is to read that percentage as the measure of your cover," Raquel Domínguez warns. On its own, it is not enough: annual limits, where they exist, eligible expenses and the conditions attached to each benefit decide what is actually paid. Claims also have deadlines, sometimes as short as fifteen days, and require an itemised invoice, the prescription and a medical report.
Premium policies go further: 100% of eligible medical expenses and prescribed medication, with no annual limit, and benefits such as dental cover of up to €9,000 or a spa stay (balneario) after a hospital admission. "This is the high end, not the reimbursement market in general," the mediator points out.
What does health insurance really cover when you need surgery?
An operation is not a single cost but several: the surgeon's fees, anaesthesia, the hospital stay, the operating theatre and diagnostic tests. According to Raquel Domínguez, a policy can cover surgery in general while excluding or limiting specific procedures, or subjecting them to long waiting periods: with some insurers, risk-reducing surgery for breast and gynaecological cancers can carry a wait of up to 48 months.
She advises checking which procedures are excluded, whether surgeons' fees are capped and which treatments need prior authorisation (autorización previa). "A missed authorisation can turn a covered treatment into an unpaid one," she stresses.
Are psychology sessions covered?
Psychological care, for children and adults alike, is among the most limited benefits, the mediator says. A typical network policy covers around 20 sessions a year, extended to 40 for policyholders up to the age of 24 and for situations such as eating disorders, bullying at school, cyberbullying, work stress or family violence. Reimbursement policies may require a prescription from a psychiatrist, or from a paediatrician for children up to 14, and may reduce the reimbursement rate as sessions add up.
What is the difference between a waiting period and a pre-existing condition?
The two are often confused, and for Raquel Domínguez the difference is decisive: "one is a matter of time, the other of underwriting."
A waiting period (carencia) is the time during which certain benefits do not yet apply. Emergencies are exempt. The usual durations:
| Benefit | Usual waiting period |
|---|---|
| Minor surgery, CT scan, MRI | 6 months |
| Major surgery, hospitalisation, childbirth | 8 months |
| Transplants, assisted reproduction | 12 months |
A pre-existing condition (preexistencia) is any illness, symptom or diagnosis that predates the start of the policy.
If you switch insurer, the new one can generally waive waiting periods if you have been insured for at least six months and keep the last premium receipt, the policy and the medical card. Ask whether cover in your home country counts too. But waiving waiting periods does not mean accepting pre-existing conditions: anything diagnosed under the previous policy becomes pre-existing for the new one, "something most people do not know," the mediator notes.
Under Ley 50/1980 de Contrato de Seguro, the health questionnaire (cuestionario de salud) must be answered accurately. The insurer may then accept the risk, exclude a condition, cover it with a surcharge or decline. An inaccurate declaration can compromise a claim later on.
Is a Spanish health insurance policy for life?
Under article 22 of Ley 50/1980, policies renew tacitly, and either party can oppose renewal in writing: one month before expiry for the policyholder, two months for the insurer. Separately, Raquel Domínguez explains, some insurers contractually waive that right once the policy has been in force for three consecutive years, in network and reimbursement products alike. The contract then becomes lifelong (vitalicia) on the insurer's side, although premiums are still reviewed every year and an inaccurate health questionnaire still allows the insurer to refuse renewal.
This matters, because most insurers only accept new applicants up to the age of 65 or 70, a few up to 75, rarely beyond. "Changing policy later in life is not always possible," she reminds us.
Does the insurance cover you everywhere, on the islands and abroad?
A national network says little about your own island or town. Ibiza is the clearest example, according to Raquel Domínguez: the island has a limited number of certain specialists and centres, so most foreign residents there choose reimbursement, to be free to get treatment elsewhere. Premiums there have also risen sharply. "In my practice, I have seen contracts almost double this year," she says. For one of her clients, the monthly premium went from €118 in March 2026 to €219.70 in October, an 89% increase in seven months for the same policyholder.
Almost every policy includes travel assistance, often run by a separate assistance company with its own network of providers, up to a limit per claim (up to €30,000 at the high end) and for trips of no more than 180 consecutive days. Reimbursement abroad depends on the tier. A network policy may only reimburse serious illnesses diagnosed in Spain, at 80% and up to an annual cap. A premium policy can reimburse treatment worldwide on the same terms as in Spain, provided you meet a minimum residence requirement, which varies by insurer and can reach 183 days a year.
Raquel Domínguez cites a case from her own practice that shows the gap. A client who fell ill in Poland needed an antibiotic. A video consultation with a doctor in Spain produced a digital prescription within minutes. The pharmacy refused it: it was not a paper original, and it was not signed by a doctor registered in Poland. The client was sent to a private clinic and paid around €600 to be examined and given a local prescription. "The assistance existed on paper; the medicine did not," she sums up. She has seen the same pattern in Colombia, where assistance policies referred patients to partner centres that then refused to treat them.
What are the advantages for companies and the self-employed?
Group policies often offer more flexible medical underwriting and waiting periods, the mediator notes. Premiums paid by the company are not taxed as income for the employee up to €500 per person per year (€1,500 in the case of disability). Self-employed workers (autónomos) under the direct estimation regime can deduct up to €500 per person. Premium policies can also be taken out at company level, for teams that are constantly on the move.
How do you choose your policy and compare quotes, step by step?
Raquel Domínguez recommends working through it in this order:
- Firstly, start from your administrative situation: visa, residence permit, entitlement or not to public healthcare or to the convenio especial. That is what sets the legal minimum for your cover.
- Secondly, ask for two or three quotes with your exact age and start date, stating whether the insurance is for a visa.
- Thirdly, choose the type of policy (network, reimbursement or mixed), looking at the real limits behind the advertised percentage.
- Fourthly, list the exclusions (pre-existing conditions, dental, optical, medication) and the procedures that require prior authorisation.
- Fifthly, check the waiting periods, and ask whether they can be waived if you are coming from another insurer.
- Sixthly, fill in the health questionnaire accurately, and ask how your pre-existing conditions will be treated.
- Seventhly, check the maximum joining age and whether there is a lifelong renewal clause.
- Eighthly, test the policy against your real life: the network doctors where you live, the language in which the insurer answers you, and your cover when you travel.
- Finally, put it through concrete scenarios: a complex surgery, six months of rehabilitation, a specialist who is not in your town or on your island, a diagnosis while abroad.
"That is where the architecture of a contract becomes visible," the mediator concludes. "The useful question is not what the policy covers. It is how you can use that cover on the day you need it."
Frequently asked questions
Is private health insurance compulsory in Spain?
Not for everyone. It is required for certain residence permits, such as the non-lucrative residence visa, with cover equivalent to the public system. It is also the main route to healthcare for residents who are not entitled to the public system.
Is the convenio especial enough for a residence visa?
No, not for a visa applied for from abroad. It requires you to be registered in a Spanish municipality and to have at least one year of residence. It therefore comes after you have settled, not before.
How much does the convenio especial cost?
€60 a month under 65 and €157 a month from the age of 65. Medication bought at the pharmacy is not covered.
Why is a policy with copayments refused for the visa?
The consulate asks for cover equivalent to the public system. In practice, according to Raquel Domínguez, consulates generally ask for a policy with no copayments or waiting periods: a policy that includes them risks being refused.
How long does a waiting period last?
Generally six months for minor surgery, CT scans and MRI, eight months for major surgery, hospitalisation and childbirth, and twelve months for transplants or assisted reproduction. Emergencies are exempt.
Is an illness that has already been diagnosed covered by a new policy?
Not automatically. A pre-existing condition is assessed through the health questionnaire: the insurer may accept it, exclude it, cover it with a surcharge or decline the contract. According to Raquel Domínguez, even if a new insurer waives the waiting periods, that does not mean it accepts pre-existing conditions.
Up to what age can you take out health insurance in Spain?
According to Raquel Domínguez, most insurers accept new applicants up to the age of 65 or 70, a few up to 75, rarely beyond.
Does Spanish health insurance cover you abroad?
Almost every policy includes travel assistance, capped per claim and limited to trips of 180 consecutive days. Reimbursement of treatment abroad depends on the tier: limited to serious illnesses for a network policy, worldwide for some premium policies.
Are health insurance premiums tax-deductible in Spain?
Premiums paid by the employer are not taxed as income for the employee up to €500 per person per year (€1,500 in the case of disability). Autónomos under the direct estimation regime can deduct up to €500 per person.
This article is for information purposes only. Conditions vary between insurers and contracts: always read the general and specific conditions of your policy.
Sources
- Ministerio de Sanidad, "Convenio especial de prestación de asistencia sanitaria": sanidad.gob.es
- Consulate General of Spain in Paris, "Visado de residencia no lucrativa": exteriores.gob.es
- Generalitat Valenciana, procedure no. 17044: sede.gva.es
- Ley 50/1980, de 8 de octubre, de Contrato de Seguro, article 22 (BOE)
Our expert
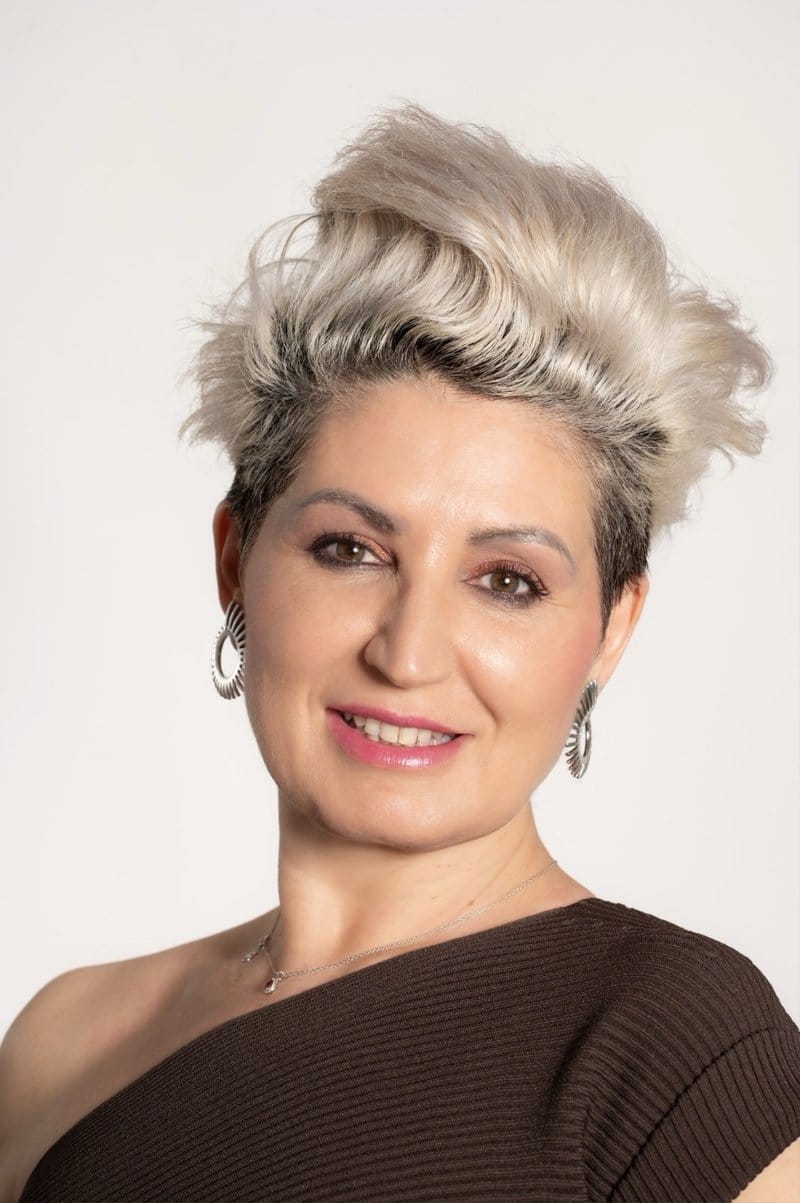
Raquel Domínguez is an insurance mediator in Palma de Mallorca. She advises international residents, mobile professionals and companies on health and personal insurance. She has more than ten years' experience in the sector and spent fifteen years living abroad.
Exclusive agent, Aegis & Aqua S.L., DGSFP registration no. C0139B10916120.
Instagram: @raqueldominguezseguros
Suis-nous sur Instagram : @thedailyvalencia
Le Livre blanc 2026 de l'expat
NIE, empadronamiento, fiscalité, école, logement : tout l'essentiel pour s'installer, réuni dans un guide PDF. Laisse ton e-mail, on te l'envoie.
🎉 Et voilà ! Ton Livre blanc 2026 de l'expat s'ouvre ici :
Ouvrir le Livre blanc 2026Dernière étape pour rejoindre l'aventure : confirme ton inscription dans l'e-mail qu'on vient de t'envoyer.
Réagis à cet article